7 min read · Last updated October 26, 2026
- Workers’ compensation, not a regular group health plan, is the exclusive remedy for a job injury in every state, meaning it is the only coverage and the only legal route against the employer for a compensable workplace injury.
- In California, an employer must hand over a workers’ compensation claim form within one working day of learning about the injury, and must authorize up to $10,000 in appropriate medical treatment within one working day of receiving it back, according to the state’s own Division of Workers’ Compensation (DWC).
- Federal rules under the Code of Federal Regulations (CFR), specifically 29 CFR 1904.29(b)(3), require most employers to log a recordable workplace injury within 7 calendar days of learning about it, a separate clock from any state comp-claim deadline.
- Billing a work injury to a personal health plan before the comp claim is sorted out can read as evidence the injury wasn’t work-related, and the health plan usually has to be repaid once the comp claim is confirmed.
A workplace injury starts a clock the employer has to beat, not the worker. In California, that means one working day to hand over a workers’ compensation claim form, and one more to authorize up to $10,000 in treatment while the claim is still pending.
In this article
- Why a workplace injury goes through workers’ compensation first
- The forms that decide it, and the clocks attached to each one
- What happens if you already used your health insurance card
- If workers’ comp denies the claim
- The first week, hour by hour
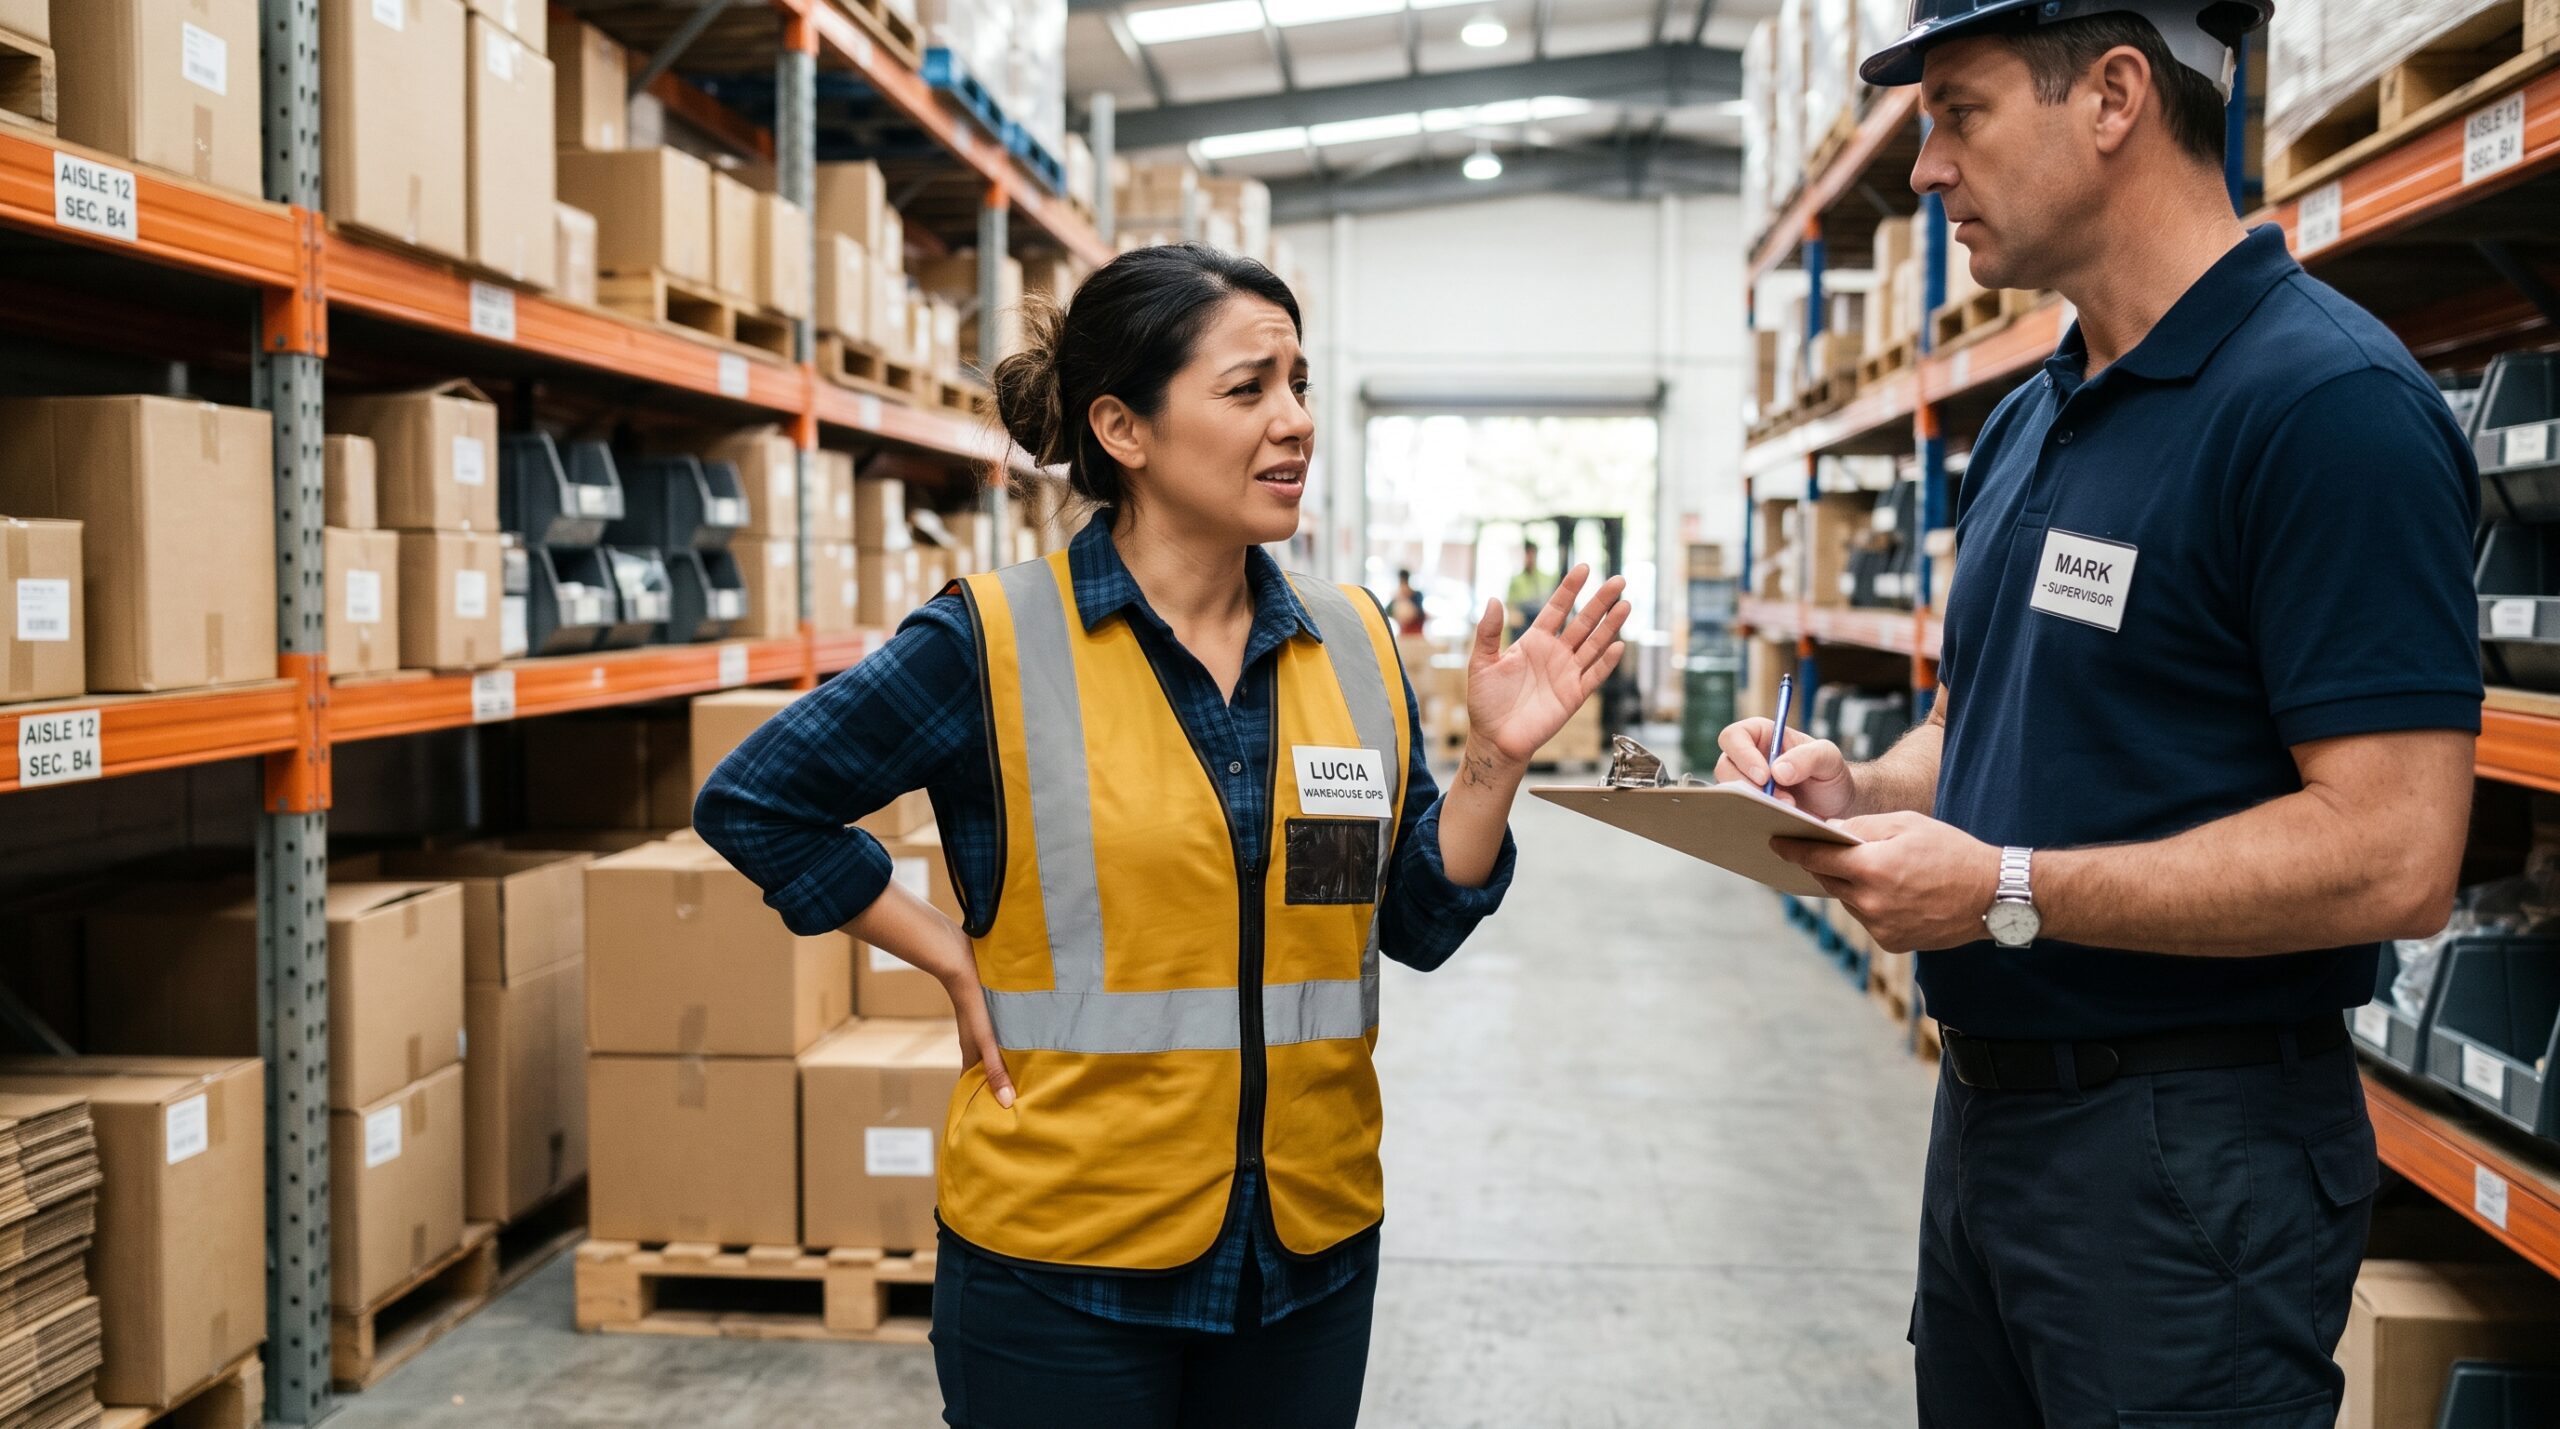
Say a worker named Felicia feels her back give out lifting a pallet on a warehouse shift. She reports it to her supervisor before her shift ends, the way her employer’s safety policy requires. That single report is what starts every clock in this article running, on a schedule she never sees and mostly doesn’t control.
Why a Workplace Injury Goes Through Workers’ Compensation First
Every state has written an “exclusive remedy” rule into its workers’ compensation law. In exchange for no-fault coverage, Felicia doesn’t have to prove her employer did anything wrong to get benefits.
In return, she generally gives up the right to sue her employer over the injury. Her employer’s workers’ comp insurer becomes the one payer responsible for her medical care and a portion of her lost wages.
Regular group health plans are built around that arrangement, not against it. Most plan documents exclude or coordinate around a work-related injury specifically because workers’ comp is supposed to be the primary payer by law.
Billing a group health plan first doesn’t just risk a denial. It can create a paper trail that looks like the injury is being treated as personal rather than occupational, which is exactly the question a comp claim is supposed to settle.
The forms that decide it, and the clocks attached to each one
The clock on a workplace injury starts the moment it’s reported, and several separate deadlines run at once from that point, each owned by a different party.
California’s Division of Workers’ Compensation (DWC) publishes a clear, publicly stated version of the sequence: the employer must provide a workers’ compensation claim form within one working day after the injury is reported, and once the completed form comes back, the employer must authorize up to $10,000 in appropriate medical treatment within one working day, even before the claim is formally accepted or denied. That $10,000 is meant to cover real, immediate care while the broader claim decision is still pending, not a final settlement figure.
A separate federal clock runs on the employer’s own recordkeeping, not Felicia’s treatment. Under 29 CFR 1904.29(b)(3), most employers covered by Occupational Safety and Health Administration (OSHA) recordkeeping rules must enter a recordable injury on the OSHA 300 log within 7 calendar days of learning about it. Missing that deadline is a recordkeeping violation, separate from and in addition to whatever the comp claim itself decides.
Every state sets its own exact claim-form and reporting deadlines, and they vary; California’s one-working-day rule is a documented, publicly stated example, not a national standard. The reporting principle it illustrates, that the clock starts the moment the injury is reported, holds everywhere.
What happens if you already used your health insurance card
Felicia reported her injury before any care happened, but that isn’t how it goes for everyone. A worker who goes straight to urgent care from the job site, before anyone has sorted out whether the injury is work-related, often hands over a personal health plan’s card out of habit, the same one used for every other appointment.
That isn’t a dead end. RAC’s guide to the insurance-card mix-up walks through what to say at intake and the separate state-by-state reporting deadlines that run alongside the clocks covered here.
The short version: tell the treating provider’s billing office, in writing if possible, that the visit was for a workplace injury and that a workers’ comp claim is being filed. The health plan can place the claim on hold pending the comp outcome, and if workers’ comp accepts the claim, it’s typically repaid through the comp insurer rather than the worker owing the difference out of pocket.
If workers’ comp denies the claim
A denial isn’t the end of either option. Felicia can appeal the comp denial through her state’s workers’ compensation board, and while that appeal is pending, or after a final denial, her personal health plan becomes the payer of last resort for treatment that is otherwise covered under her plan’s own terms. Keep every denial letter and claim-form copy; both the comp appeal and a health-plan claim will ask for them.
The first week, hour by hour
| Step | Deadline (California model) | Who it falls on |
|---|---|---|
| Report the injury to a supervisor | As soon as possible after the injury | Injured worker |
| Provide the workers’ comp claim form | Within 1 working day of the report | Employer |
| Authorize up to $10,000 in interim medical treatment | Within 1 working day of receiving the completed form | Employer / claims administrator |
| Enter the injury on the OSHA 300 log, if recordable | Within 7 calendar days of learning about it | Employer (federal rule, every covered state) |
Frequently asked questions
What if I already gave the hospital my own health insurance? Tell the billing office in writing that the visit was for a workplace injury and that a workers’ comp claim is being filed. The health plan can hold the claim pending the comp outcome, and if comp accepts the claim, it typically repays the health plan directly.
Do I have to see the doctor my employer picks? It depends on the state and whether the employer has a pre-designated medical provider network in place before the injury happens. Ask the claims administrator directly which rule applies, since this is one of the clearest ways a claim gets delayed when it’s assumed rather than confirmed.
What if my employer says this isn’t a workers’ comp case? An employer’s opinion doesn’t decide the claim. File the claim form anyway and let the workers’ comp insurer or board make the actual determination; a disputed claim can still be appealed if it’s denied.
What happens to my health insurance claim if workers’ comp denies the case? Once a denial is final, or while an appeal is pending, a personal health plan typically becomes the payer for treatment that’s otherwise covered under the plan’s own terms. Keep the denial letter; the health plan will likely ask for it.
Is the one-working-day rule the same in every state? No. California’s rule is a documented, publicly stated example, not a national standard. Every state sets its own claim-form and reporting deadlines, so confirm the exact timeline with the state workers’ compensation agency where the injury occurred.
Leave a Reply